

Entrusted imports
A fire, leak or forklift incident can damage customer goods. The operator's legal responsibility and the trigger for direct goods cover may differ.
Try a different word, or check the spelling.
Releasing imported stock means accounting for the goods and the customs obligations, not just unlocking a bay. Your customs bond is not cargo insurance; warehouse protection still needs to distinguish customer property, release errors, and the building you operate.
Talk with The Southern Agency about your operation, policy terms, and the information carriers need.
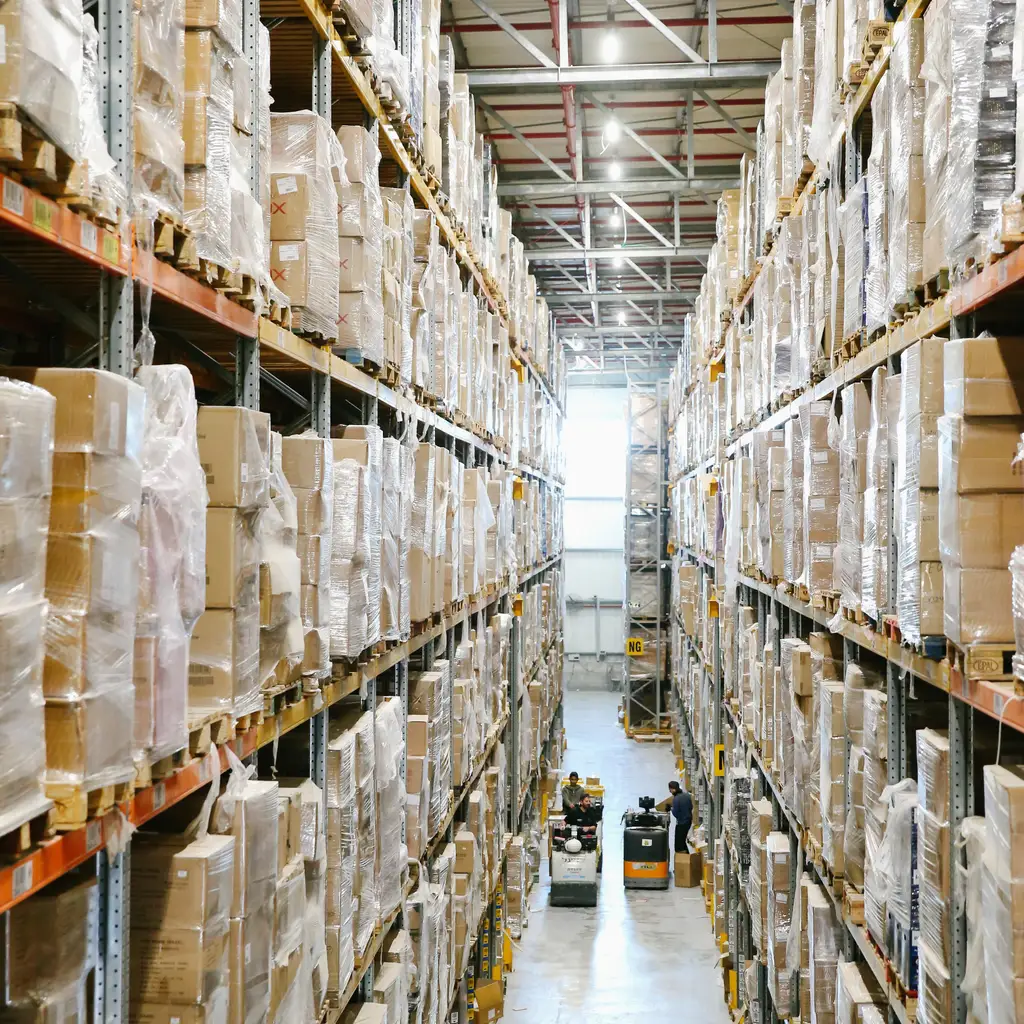
You manage imported goods for customers, handling everything from initial receipt to authorized release. A missing item or inventory error can quickly turn a routine shipment into a serious dispute regarding your records and custody.
The Southern Agency can review your warehouse operations to help you select insurance that addresses your property and legal liability. For example, we can examine how your coverage handles entrusted imports versus your own warehouse equipment and buildings.
A fire, leak or forklift incident can damage customer goods. The operator's legal responsibility and the trigger for direct goods cover may differ.
Missing stock or release to the wrong party can produce commercial and customs issues. Physical-loss cover does not automatically insure documentation mistakes.
Theft, employee dishonesty, and unexplained shortages need different proof and terms. Staff and visiting drivers also face material-handling injuries.
Policies to ask about. Which ones fit depends on your operations, your contracts, and the carrier’s forms.
These hypothetical examples are not agency claim results. Whether a loss is covered depends on the facts, policy terms, and applicable exclusions.
Electronics are stolen overnight. Applicable customer-goods/theft terms may address a covered loss, subject to ownership, limits, and evidence. A customs obligation is a separate question.
A sprinkler incident damages customer imports. Direct goods cover or warehouse liability may respond under different triggers; negligence is not established merely by damage.
A forklift damages an imported unit during release. Suitable custody cover may address covered physical damage. Incorrect release paperwork or penalties require separate analysis.
Start with the work you do and the questions your current policies leave unanswered. Carrier options depend on your location, risk, and underwriting. Explore our approach.
No. Legal-liability terms generally require an insured liability; a direct property form has a different trigger.
No. It secures specified obligations and is separate from warehouse or cargo insurance.
Do not assume so. Fines, penalties, and documentation errors need specific legal and policy review.
Not necessarily. Evidence, insured cause, and shortage/disappearance exclusions matter.
Bring your questions, current policies, and relevant contracts. An agent can review coverage terms, exclusions, and the information carriers ask for, then explain the options available to you.