

Theft and employee access
Burglary, robbery, and employee misappropriation have different definitions. Client funds or bullion are not automatically covered by a generic theft agreement.
Try a different word, or check the spelling.
A locked vault does not make bullion, cash, artwork, and documents the same insured property. Your valuables protection needs the actual contents, values, and custody arrangements, with employee theft and unexplained disappearance distinguished from building security equipment or an ordinary liability limit.
Talk with The Southern Agency about your operation, policy terms, and the information carriers need.
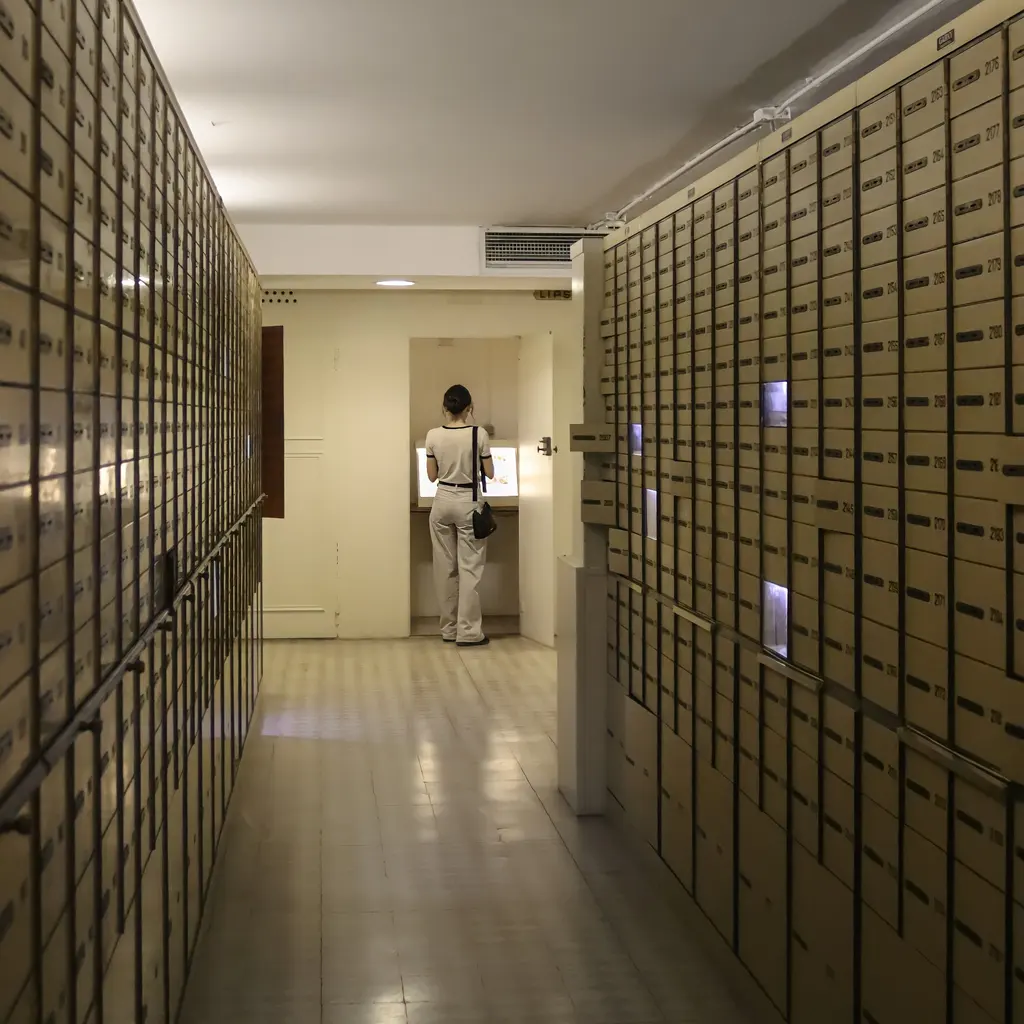
You store high-value items like bullion, jewelry, or confidential documents for clients who require strict access control. A security lapse or custody error can lead to complex claims, as ordinary property policies often exclude these types of assets.
The Southern Agency can review your security protocols and custody arrangements to help you select appropriate specialized coverage. We can discuss how to tailor your insurance to reflect the high value of the client property inside your vault versus your own structural and security equipment.
Burglary, robbery, and employee misappropriation have different definitions. Client funds or bullion are not automatically covered by a generic theft agreement.
Unexplained shortages may be excluded. Legal responsibility and direct property cover have different triggers and valuation provisions.
Security conditions can affect cover. Fire or water can still damage contents, and cash/art/document values need appropriate specialist treatment.
Policies to ask about. Which ones fit depends on your operations, your contracts, and the carrier’s forms.
These hypothetical examples are not agency claim results. Whether a loss is covered depends on the facts, policy terms, and applicable exclusions.
Intruders defeat controls and steal contents. Suitable valuables/crime or custody cover may address an insured interest if definitions, security conditions, and limits fit.
An audit identifies employee theft. Applicable fidelity terms may respond, subject to covered property, ownership, discovery, and proof; all losses are not automatically separate full limits.
A reconciliation finds missing items without a known cause. Disappearance or inventory-proof exclusions may prevent payment even with a high selected limit.
Start with the work you do and the questions your current policies leave unanswered. Carrier options depend on your location, risk, and underwriting. Explore our approach.
Not automatically. Money, securities, and precious-metal exclusions or sublimits require specialist review.
Not by itself. Valuables property/crime excess must be specifically arranged under applicable terms.
No. Proof, discovery, and exclusions can produce different outcomes.
No. They help define obligations but do not replace the required policy interest and trigger.
Bring your questions, current policies, and relevant contracts. An agent can review coverage terms, exclusions, and the information carriers ask for, then explain the options available to you.