

Property accumulation
Fire, water, or racking incidents can damage multiple lots. Stock mix, maximum values, and protection systems affect terms.
Try a different word, or check the spelling.
A fire or leak can affect stock belonging to several customers at once. Review whose goods you insure, how they are valued and what your storage agreements make you responsible for.
Call with your warehouse receipts, peak owned and customer stock values, and any handling services beyond storage.
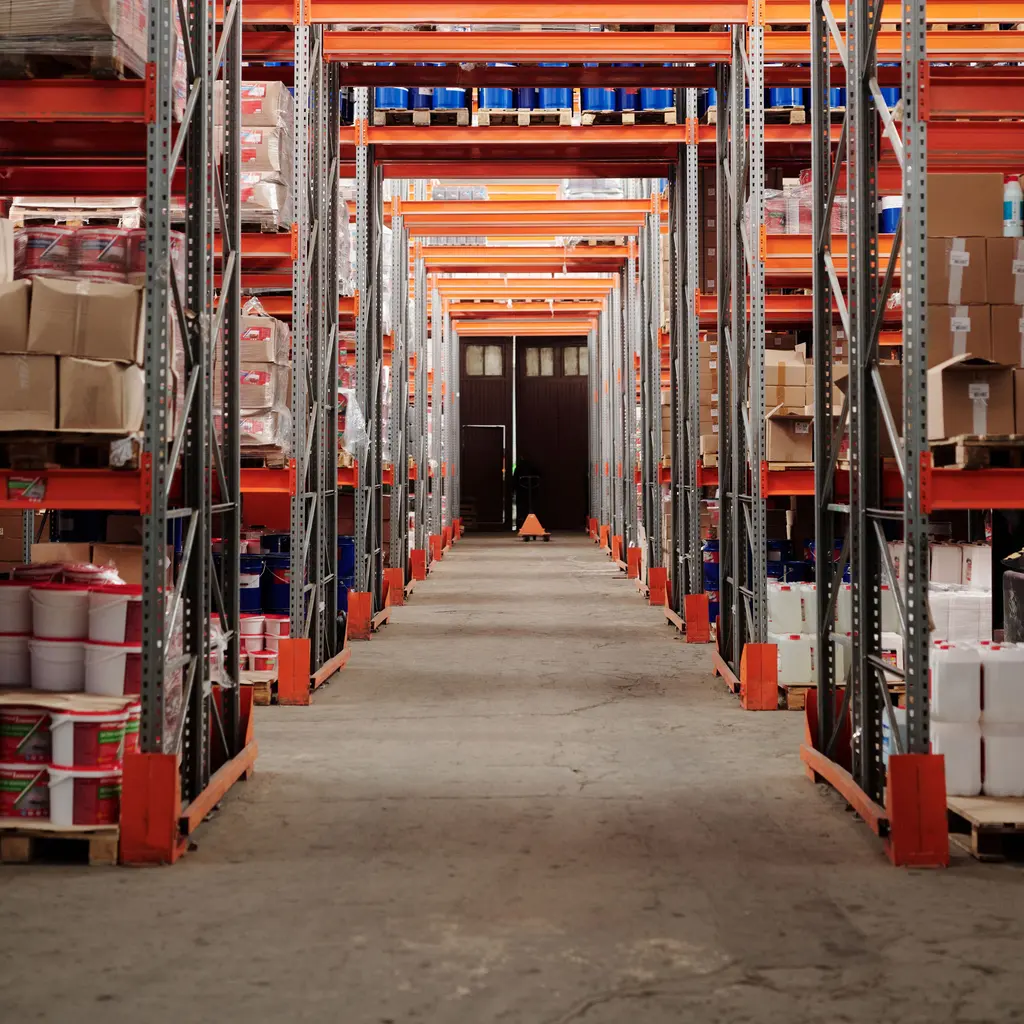
You receive, store and dispatch a mix of dry goods that may belong to you, your customers or both. A leak, fire or handling accident can damage a large concentration of stock and leave several owners seeking payment.
The Southern Agency can review your warehouse receipts, handling services, and ownership responsibilities to help you choose insurance. We can discuss property protection for your own assets separately from coverage for customer goods in your care.
Fire, water, or racking incidents can damage multiple lots. Stock mix, maximum values, and protection systems affect terms.
A forklift may damage customer goods. Legal liability is not established solely because property was on-site, and direct cover has a different trigger.
Known theft differs from unexplained shortage. A shutdown can reduce storage income, but customer delay penalties are separate.
Policies to ask about. Which ones fit depends on your operations, your contracts, and the carrier’s forms.
These hypothetical examples are not agency claim results. Whether a loss is covered depends on the facts, policy terms, and applicable exclusions.
A sprinkler leak damages operator and client stock. Property and custody cover may address different interests and triggers; water cause, values, and limits still matter.
A forklift damages customer goods. Appropriate warehouse legal liability may address covered responsibility; a GL custody exclusion can leave ordinary premises cover insufficient.
An employee is injured at the dock. Workers compensation may provide eligible benefits, while a carrier's visitor claim would raise separate liability questions.
Start with the work you do and the questions your current policies leave unanswered. Carrier options depend on your location, risk, and underwriting. Explore our approach.
No. The policy's legal-liability trigger and exclusions apply; direct customer-goods cover is a different option.
No. Proof and disappearance exclusions matter.
Yes. Limits, reporting, and any seasonal increases must reflect maximum insured values.
Business income coverage may help replace lost storage or handling income after a covered loss interrupts operations. Review the time needed to repair racks, replace equipment and reopen, plus any waiting period. Customer delay penalties and ordinary loss of business are separate questions.
Bring your questions, current policies, and relevant contracts. An agent can review coverage terms, exclusions, and the information carriers ask for, then explain the options available to you.