

Damage to stored records
Fire, roof leaks, or sprinkler discharge can damage boxes and media. The cost of restoring records may differ greatly from replacing blank paper, and some information may be impossible to reconstruct.
Try a different word, or check the spelling.
Replacing a box of paper is not the same as reconstructing the information your client entrusted to it. Records protection should account for that value and your retrieval or destruction duties, without assuming digital-index cover includes a paper disclosure or irreplaceable files can be restored.
Talk with The Southern Agency about your operation, policy terms, and the information carriers need.
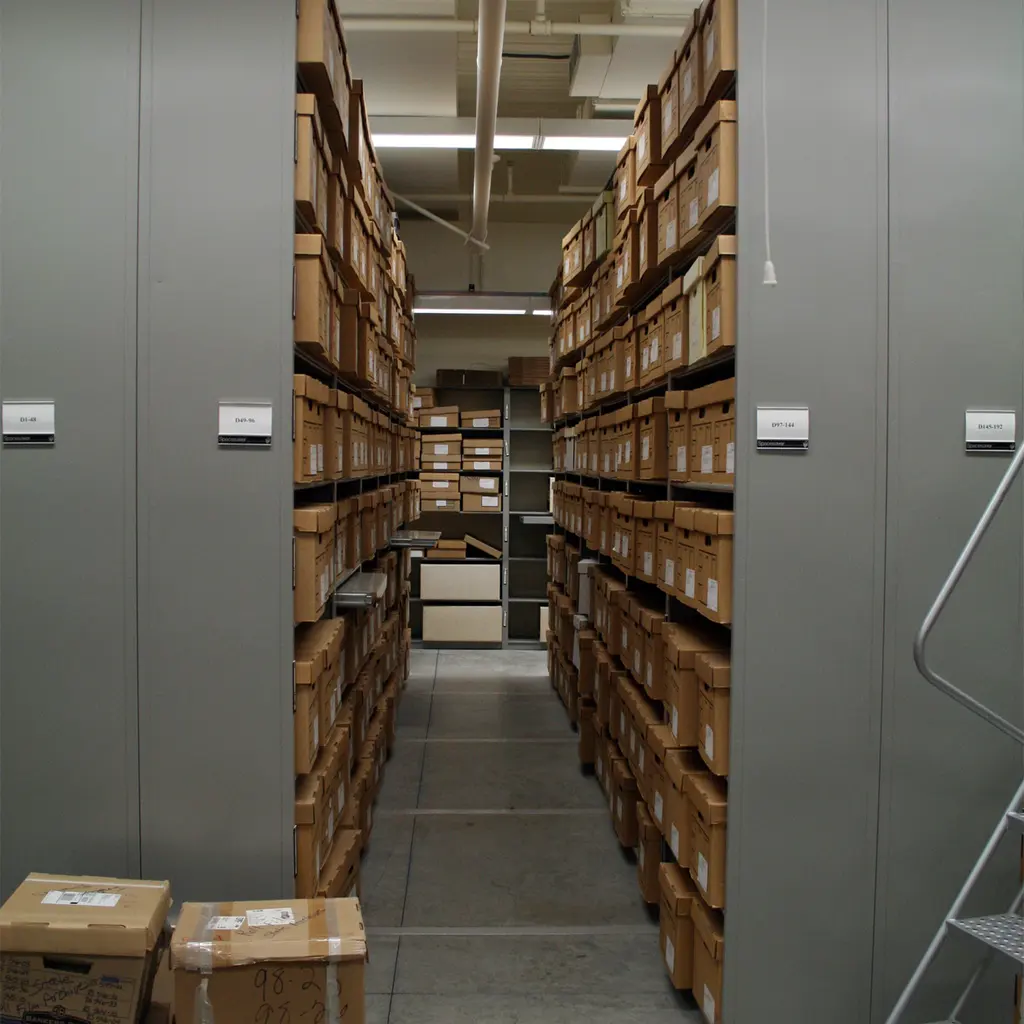
You keep sensitive client records and media secure, organized, and ready for retrieval upon request. A misfiled box or an error during an authorized destruction can lead to significant client claims, regardless of whether a physical fire or theft occurred.
The Southern Agency can review the records you hold, your retrieval and destruction duties and the value your agreements assign to client files. We can help separate building and equipment protection from custody, service-error and confidentiality coverage, including disclosures involving paper rather than a digital index.
Fire, roof leaks, or sprinkler discharge can damage boxes and media. The cost of restoring records may differ greatly from replacing blank paper, and some information may be impossible to reconstruct.
A misidentified box can be sent to the wrong recipient or destroyed before authorization. The resulting confidentiality or financial-loss claim may arise even if the storage building is unharmed.
An electronic index can reveal sensitive information or become unavailable after an attack. Scanned records and stored media also need to be included in the data discussion.
Clients and couriers visit loading and retrieval areas while staff move boxes. Physical injury, damage to goods in custody and an employee's work-related injury raise different coverage questions.
Policies to ask about. Which ones fit depends on your operations, your contracts, and the carrier’s forms.
These hypothetical examples are not agency claim results. Whether a loss is covered depends on the facts, policy terms, and applicable exclusions.
Water enters through a damaged roof and soaks stored boxes. A records or custody form may help with eligible restoration costs or the operator's covered liability. Roof-leak conditions, valuation, and client-property limits matter; building insurance alone does not establish payment for the files.
Staff send a client's records to another account and the client makes a confidentiality claim. Professional or privacy coverage may respond if the service and paper disclosure are included. Digital-only cyber terms may leave a gap.
A scheduling error sends boxes for destruction before the client approves it. Professional liability may help with a covered negligence claim. The policy's insured-services description and contractual-liability terms determine whether the loss fits; ordinary property coverage does not insure every records-management error.
Start with the work you do and the questions your current policies leave unanswered. Carrier options depend on your location, risk, and underwriting. Explore our approach.
Not by itself. The policy must address the relevant interest in client property and the costs sought. Restoration, reconstruction, and legal liability may have separate terms.
An indexing mistake or premature destruction can cause financial harm without covered physical damage. E&O needs to include the records-management services performed.
Some privacy forms may, but the definition of covered information and event must include the incident. Ask about a misdelivered box rather than assuming a cyber label is sufficient.
Review reconstruction costs, agreed values, liability caps, and policy sublimits with the agent. No valuation method can make unavailable information recoverable.
It depends on the insured dishonest act and type of covered loss. Privacy response or client liability can require different coverage even when an employee was involved.
Bring your questions, current policies, and relevant contracts. An agent can review coverage terms, exclusions, and the information carriers ask for, then explain the options available to you.